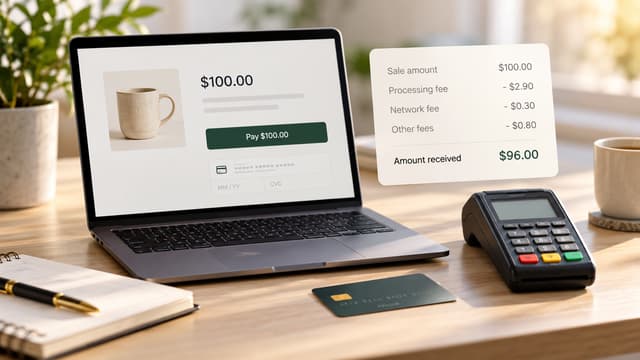
The customer pays $100. The business gets less.
A customer buys something online for $100. Their bank approves the payment, the checkout page confirms the order, and the business records a $100 sale. But the amount available to the business can be several dollars smaller.
Under Stripe's standard US pricing for a domestic online card payment, the processing charge is 2.9% plus 30 cents. On a $100 sale, that works out to $3.20. The business is left with $96.80 before the cost of the product, shipping, advertising, taxes and other expenses.
That difference is the cost of accepting the payment. It pays for a system involving banks, card networks, payment processors and the infrastructure that moves money between them.
The precise amount is not universal. A different provider, payment method, card type or country can produce a different fee on the same $100 purchase.
How a $100 card payment becomes $96.80
Most small businesses encounter payment processing fees as a combination of a percentage and a fixed amount per transaction.
Using the standard Stripe example, 2.9% of $100 is $2.90. Add the fixed 30-cent fee and the processing cost becomes $3.20.
Subtract that from the payment and $96.80 remains. This is the amount after this particular processing fee, not the business's profit. Other fees, operating costs and settlement adjustments may still apply.
The fixed charge matters because it is imposed on each payment, regardless of whether the customer spends $10 or $1,000.
| Part of the transaction | Amount |
|---|---|
| Customer payment | $100.00 |
| Percentage fee (2.9%) | $2.90 |
| Fixed transaction fee | $0.30 |
| Total processing fee | $3.20 |
| Remaining after processing | $96.80 |
Stripe, PayPal and Square do not charge the same price
Three familiar payment providers illustrate how much the price can change without changing the amount a customer spends.
For a $100 domestic online payment, Stripe's standard card rate produces a $3.20 fee. Square's Free plan lists a higher rate for its regular online payment category, while a transaction paid through PayPal's branded checkout has its own pricing.
These are examples of specific US payment products, not a claim that one provider is always cheaper. Square charges different rates by plan and payment channel. PayPal's card-processing products have different rates from payments made through PayPal Checkout. Businesses may also qualify for negotiated pricing.
| US payment service | Published rate | Fee on $100 | Remaining |
|---|---|---|---|
| Stripe, standard domestic card | 2.9% + 30¢ | $3.20 | $96.80 |
| Square Free, online payment | 3.3% + 30¢ | $3.60 | $96.40 |
| PayPal Checkout, PayPal payment | 3.49% + 49¢ | $3.98 | $96.02 |
Who actually receives the processing fee?
The company whose name appears on the payment dashboard does not necessarily keep the entire fee.
Card processing has several underlying costs. Interchange is associated with the bank that issued the customer's card. Assessment fees go to the card network, such as Visa or Mastercard. The payment processor or acquiring provider also charges for its services.
Under flat-rate pricing, these costs are generally bundled into a single advertised charge. A business paying 2.9% plus 30 cents does not usually see every underlying fee separated on each transaction.
With interchange-plus pricing, the card-network and issuing-bank costs are passed through more explicitly, with a processor markup added on top. This can provide greater visibility, although the final cost depends on the cards customers use and the business's agreement.
That is why two businesses processing the same sales volume may not pay the same effective rate.
Small payments can be surprisingly expensive
A percentage-based fee increases with the size of the payment. A fixed fee does not. That makes the fixed portion disproportionately expensive on low-value orders.
At 2.9% plus 30 cents, a $10 transaction costs 59 cents to process. That is 5.9% of the sale. On a $1,000 transaction, the fee is $29.30, or 2.93%.
The effect becomes more obvious when a business collects many small payments. Ten separate $10 transactions generate $5.90 in processing fees. One $100 transaction generates just $3.20 under the same rate.
This is one reason payment size matters to businesses selling inexpensive digital products, individual downloads or low-cost subscriptions. The per-transaction charge can consume a significant share of the revenue.
| Payment | Processing fee | Effective fee rate |
|---|---|---|
| $5 | $0.45 | 9.0% |
| $10 | $0.59 | 5.9% |
| $100 | $3.20 | 3.2% |
| $1,000 | $29.30 | 2.93% |
International customers can change the calculation
An online store can sell to someone thousands of miles away without either party noticing much difference at checkout. The payment processor may notice immediately.
Cross-border payments can carry additional charges because the customer's card was issued in another country. Currency conversion can introduce another charge when the customer's payment and the business's settlement involve different currencies.
For example, Stripe's published US standard pricing adds 1.5 percentage points for international cards and another 1 percentage point when currency conversion is required.
At those rates, a $100 card transaction with both additions would incur $5.70 in processing fees rather than $3.20, assuming no other charges. The result is specific to this pricing arrangement; international fees differ between processors and markets.
Businesses serving customers worldwide need to look beyond the domestic rate displayed most prominently on a pricing page.
What happens when the customer gets a refund?
A refund reverses the customer's payment, but it does not necessarily reverse the cost of having processed it.
Stripe says its original processing fees are not returned when a payment is refunded. PayPal and Square likewise state that the fees originally charged to process a refunded payment are not returned.
Consider a $100 Stripe card sale that originally incurred a $3.20 processing fee. If the merchant subsequently issues a full refund, the customer receives $100 back, while the business still bears the original $3.20 processing cost. The exact accounting and refund charges depend on the provider and pricing arrangement.
A chargeback can be more expensive. If a cardholder disputes a transaction through their bank, the merchant may face the loss of the disputed payment, an additional dispute fee, and the cost of investigating or contesting the claim.
Refunds and disputes are different processes. A voluntary refund is generally initiated by the business. A chargeback begins through the cardholder's bank and follows card-network dispute rules.
Could a bank payment cost less than a card?
Sometimes. Credit and debit cards are convenient, but they are not the only way to collect money online.
In the United States, Automated Clearing House payments, or ACH, move funds through the banking system rather than the traditional card networks. Some providers charge lower percentage fees or impose a cap on the fee for larger payments.
Stripe, for example, lists ACH Direct Debit at 0.8% with a $5 cap under its published US pricing. On a $100 payment, that base rate produces an 80-cent fee. That is less than the $3.20 standard domestic card example.
But a cheaper fee does not automatically make one payment method better. Bank debits have different settlement times, authorization requirements, return risks and customer experiences. Extra charges may apply in particular situations.
The right comparison is between payment methods that actually work for the customers and transactions a business handles.
The rate on the pricing page is only the beginning
A small business comparing payment processors should start with the rate for the payment method its customers are most likely to use, not simply the lowest number advertised.
The next questions concern transaction size, international cards, currency conversion, refunds, disputes, payout charges and any monthly software fees. A processor with a slightly higher domestic card rate might still be a better fit because of the payment methods, checkout features or administrative tools it provides.
It also helps to distinguish sales revenue from the money the business can actually keep. A $100 order can produce $96.80 after one processing fee, but inventory, shipping, refunds, marketing and taxes still determine whether the sale was profitable.
The checkout may take only a few seconds. Understanding what happens to the money afterward requires looking at the full cost of accepting it.